Instacart Shopper Rewards
Branch Messenger
- 4.3
- 140.00 Reviews
- 100.00K
- Downloads
- Free
- Price
Screenshots
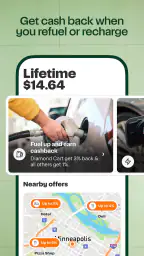
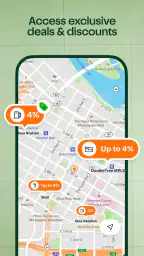
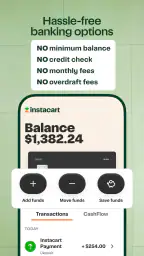
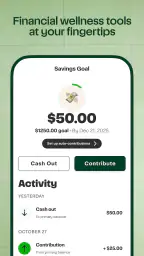
Instacart Shopper Rewards Pros and Cons
Pros
- Rewards can add extra value to regular shopping activity.
- Clear progress tracking helps you monitor available rewards.
- Useful for shoppers who already complete frequent Instacart orders.
- Offers may encourage better planning around eligible purchases.
- Digital access makes checking rewards convenient while working.
Cons
- Reward eligibility may vary by market, order type, or shopper status.
- Some benefits can require meeting specific spending or activity targets.
- Rewards may expire if they are not used within the stated period.
- The program may provide limited value for occasional shoppers.
- Terms and reward conditions can change without much notice.
 Analysis by All-app
Instacart Shopper Rewards caught my attention because it sits in an unusual place: it is a finance app built around the working life of Instacart shoppers, not a general banking tool aimed at everyone. The store summary points to a new debit card, while the short description identifies it as Instacart Shopper. That combination tells me the app is meant to be considered alongside the shopper experience rather than treated as a replacement for a full personal-finance suite.
After spending time looking at it as a daily money tool, my view is fairly practical. The first impression is appealing if you already earn through Instacart and want a more direct way to think about shopper-related money. The harder question is whether it deserves a permanent place on your phone after the novelty of a new card wears off. For me, the answer depends less on curiosity and more on whether the app fits a repeatable routine: checking money, separating work-related spending, and deciding when the card is genuinely useful instead of simply adding another financial account to maintain.
What the first week feels like
The opening appeal is easy to understand. A debit card connected to the shopper side of your finances can feel more purposeful than a standard checking account card. If I were delivering orders regularly, I would want a clear mental boundary between money associated with that work and the rest of my household budget. Even without turning the app into a complete accounting system, that separation can make everyday decisions less vague.
The app is free, carries an Everyone age rating, and comes from Branch Messenger. Those details make it approachable for a broad audience, although the practical audience is much narrower than the age label suggests. A teenager browsing finance apps is not the natural user here; an adult who shops for Instacart and wants to examine the debit-card option is far more likely to benefit.
During the first week, I would use it with a very specific goal rather than opening it randomly. I would decide whether the card is useful for shopper-related purchases, for receiving or accessing work money, or simply for keeping a separate view of this side of my finances. That small decision matters. Without a purpose, a new finance app quickly becomes another icon that gets opened a few times and then forgotten.
The app’s current version is 2026.8.2, which gives the product a relatively current feel in the context of its release on Aug 6, 2025. I would still judge it by the consistency of my routine rather than by version numbers. A new release can make an app feel fresh, but lasting value comes from whether the same basic actions remain convenient several weeks later.
A realistic shopper routine
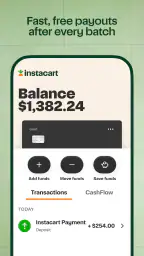
Imagine a shopper finishing an afternoon of deliveries. Instead of letting every work-related transaction disappear into a single personal account, they check the card and use that moment to review what happened during the shift. A fuel purchase, a quick meal, or another small expense can be considered in the same context as the workday. The benefit is not necessarily sophisticated analysis; it is the habit of looking at shopper money as its own stream.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
I find this kind of workflow more useful than opening a finance app only when something goes wrong. A short check after a shift can reveal whether the card is helping with organization or merely creating another balance to remember. It also gives the user a fair test: after several workdays, can they explain why they keep using the card?
One non-obvious trade-off is that separation can improve clarity while increasing mental overhead. If I already have a bank account, a budgeting app, and a personal debit card, adding a shopper-focused card may make work finances easier to see but harder to consolidate. The first week is therefore the best time to decide whether the extra boundary is genuinely helpful.
Who gets the strongest first impression
Instacart shoppers who want a dedicated money routine are the clearest audience. Someone who shops only occasionally may still like the idea, but the benefit has less time to accumulate. A frequent shopper has more opportunities to test whether the card makes work-related money easier to track and whether the app becomes a natural checkpoint after each shift.
I would be more cautious if you are searching for a complete personal-finance command center. The product’s identity is focused on the shopper and debit-card relationship, so I would not choose it simply because I want investment tracking, broad household budgeting, or a replacement for every banking service I already use. Those needs are better served by tools designed around them.
Why the value may or may not last
The app has an average rating of 4.3 from around 500 ratings, with roughly 140 written reviews. That suggests a generally positive reception, but I would treat it as a starting signal rather than proof that it will fit every shopper. Finance apps are highly personal: the same card can feel wonderfully simple to one user and unnecessarily complicated to another, especially when existing accounts already cover the basics.
Month-to-month value comes from repetition. If I use the app whenever I work, it has a chance to become part of a reliable cycle: shop, review, separate, and plan. If I only open it to admire the idea of a new debit card, its usefulness will fade quickly. The recurring question is not whether the card looks convenient on day one, but whether it reduces friction on ordinary working days.
One useful test is to give the app a defined role for several weeks. I might use the card only for expenses I associate with shopping, or I might use it as the place I check after completing work. The point is not to invent a complicated system. The point is to see whether the app helps me make a decision I was previously postponing, such as how much money is available for work-related spending or whether my shopper income is being mixed too freely with personal funds.
This reveals an important limitation: a dedicated financial tool does not automatically create financial discipline. If I do not review transactions, remember the card, or connect its use to a simple budget habit, the app cannot do that work for me. Its recurring value is strongest when I already want structure and need a focused place to practice it.
Maintenance is the real test
Every additional financial product creates maintenance, even when the app itself is easy to use. I have to remember which card I am carrying, know where money is sitting, watch for declined or unexpected transactions, and keep my broader budget accurate. A shopper who prefers one account for everything may find that simplicity more valuable than the separation offered here.
That is why I would not recommend moving all personal spending into a new shopper-focused setup immediately. I would begin with a narrow purpose and observe how often I need to move money, check balances, or explain the account to myself. If those tasks feel natural, the app earns a larger role. If they feel like chores, the usual bank card may be the better long-term choice.
A second non-obvious insight is that the app can be judged by the quality of its “closing routine,” not just its opening screen. After a shift, can I finish my money check quickly and understand what the card is doing for me? If the answer is yes, the app supports a habit. If I leave with more questions about which account to use next, the extra financial layer may be working against me.
I would also avoid treating the card as a substitute for keeping personal records. Shopper income and expenses can have consequences beyond the app, and a dedicated card does not remove the need for whatever record-keeping method suits your situation. I would use the app as one practical part of my routine, not assume it automatically handles every financial responsibility connected with independent work.
Where fatigue can appear
The main source of fatigue is repetition without a visible payoff. Checking another balance feels worthwhile when it helps me act. It feels pointless when I still need to open several other apps to understand my complete financial position. This is especially important for shoppers who work irregularly. A tool that fits a daily schedule may feel excessive when used only once every few weeks.
There is also a psychological cost to managing separate money spaces. At first, the distinction between shopper funds and personal funds can feel clean. Over time, transfers and exceptions can blur it. A personal purchase made with the shopper card, or a work expense paid from a different account, may make the system less tidy than intended. The app does not fail because of that; rather, the user has to decide how much organization is worth maintaining.
Another possible frustration is expectation. The phrase “new debit card” can make people imagine a broad set of banking conveniences, while the app’s clearer identity is its connection to Instacart shoppers. I would approach it with a focused question: does this help me manage the shopper side of my money? That is a fairer test than expecting it to replace a traditional bank, a tax workflow, and a budgeting platform at once.
If you rarely shop for Instacart, already have an excellent system for separating work expenses, or strongly prefer keeping every transaction under one established bank, I would probably skip it. The free price removes a financial barrier, but it does not remove the time cost of maintaining another account and another habit.
How it compares with familiar alternatives
The usual alternative is a regular bank debit card paired with a notes app or budgeting tool. That approach is less specialized, but it can be simpler because personal and work money remain in one familiar place. For a casual shopper, simplicity may win. You can record relevant expenses manually and avoid learning a separate shopper-oriented workflow.
A general budgeting app offers the opposite advantage. It may give a wider household view, bringing accounts and categories together instead of focusing on one work identity. If my main goal were to understand rent, groceries, subscriptions, savings, and shopper income in one picture, I would look first at that broader option. Instacart Shopper Rewards makes more sense when the shopper connection is the reason I want a separate financial space.
A third alternative is a traditional second bank account. That can provide separation without tying the idea as closely to shopper activity, which may be useful if I earn from several kinds of gig work. The trade-off is that a general account may not feel as directly connected to the Instacart routine. In my view, the choice comes down to focus versus flexibility: this app offers a focused identity, while a normal second account can adapt to more kinds of income.
The strongest reason to choose this app is therefore not that it is a finance app in the broadest sense. It is that the debit-card concept may give an Instacart shopper a clearer boundary around work-related money. The strongest reason to choose something else is that boundaries can become burdens when the work is occasional or the user already has a well-maintained system.
Small habits that improve the trial
I would start by writing down the one job I expect the app to perform. “Help me keep shopper money separate” is better than “manage my finances,” because it gives me a testable standard. I would then use the card consistently for that job instead of mixing several purposes during the first few weeks.
Next, I would set a short review moment after a work session rather than waiting for the end of the month. The review does not need to become a long budgeting exercise. I would simply ask what the balance represents, which purchases belong to the shopper routine, and whether the separation made a decision easier. This is one of the most practical ways to discover whether the app has recurring value.
Finally, I would keep my main financial system intact while testing it. That means I would not abandon my existing bank or records just because a new card feels convenient. A gradual trial exposes the real maintenance burden and makes it easier to stop using the app if it does not earn its place.
These steps also answer a question many users have after installation: should the app become the center of everything immediately? In my opinion, no. Its best chance of becoming a lasting tool comes from a limited, clearly defined role. Once that role proves useful, expanding its place in your routine becomes a decision based on experience rather than novelty.
My long-term verdict
The lasting value is in the routine, not the novelty of the card. I like the idea of a finance app that speaks directly to Instacart shoppers because it acknowledges a real problem: work money can become difficult to distinguish from everyday spending. A focused debit-card experience may make that boundary easier to maintain, especially for someone who shops often and wants a dedicated checkpoint.
At the same time, I would not recommend it automatically to every shopper. The app is free, has passed the 100K-install mark, and has a solid average rating, but popularity does not decide whether another financial account belongs in your life. The deciding factors are frequency of Instacart work, willingness to maintain a separate money habit, and whether the card solves a problem your current bank or budgeting setup leaves unresolved.
For a regular shopper, I would try it with a narrow purpose and keep using it only if the post-shift review becomes easier. For an occasional shopper, I would compare the convenience against the burden of remembering one more card. For someone seeking broad financial planning, I would choose a general budgeting or banking alternative instead.
My final impression is cautiously positive. Instacart Shopper Rewards can earn lasting space when it turns shopper finances into a simple, repeatable routine. It loses that advantage when separation creates more checking, transferring, and mental sorting than it saves. I would recommend testing it patiently, judging the ordinary month rather than the exciting first week, and keeping it only if it continues to make your working money clearer.
Frequently Asked Questions
What is Instacart Shopper Rewards?
Instacart Shopper Rewards is a benefits program connected with eligible Instacart shopper accounts. It may provide access to savings, partner offers, discounts, or other perks based on shopper activity and current program rules. The exact benefits can vary by location, shopper status, and promotional availability, so users should review the terms shown in the app before relying on a particular reward.
Who can use Instacart Shopper Rewards?
Access is generally intended for people who shop or deliver through Instacart as shoppers. Eligibility may depend on factors such as account status, region, activity, and whether the program is currently available in the shopper’s market. After signing in, check the Rewards section or account notifications to see whether your profile qualifies and which offers are available to you.
How do I earn or redeem rewards?
The way rewards are earned and redeemed depends on the specific offer. Some benefits may be activated automatically, while others require completing qualifying deliveries, meeting activity requirements, or selecting an offer in the app. Open each reward carefully to check expiration dates, minimum requirements, participating merchants, and redemption instructions before making a purchase or completing an eligible task.
Does Instacart Shopper Rewards cost anything?
The rewards program itself may be available without a separate subscription fee, but individual offers can have conditions, exclusions, or costs that are not covered by the benefit. For example, a discount may apply only to certain products or services, while taxes, delivery charges, or membership fees may remain payable. Always read the full offer details before redeeming it.
Is Instacart Shopper Rewards available on Android and iPhone?
Instacart Shopper Rewards is typically accessed through the official Instacart shopper experience on supported Android and iOS devices, although availability can depend on the app version and country. Download the official shopper app from Google Play or the Apple App Store, keep it updated, and sign in with the account connected to your shopper activity to view eligible rewards.